Mortgage vs payment plan in Dubai: compare the cash due
Compare a Dubai mortgage with a developer payment plan: cash deadlines, the 50% off-plan lending cap, finance costs and the balance due at handover.
A mortgage is property-secured finance from a lender. A developer payment plan spreads the purchase price across instalments in your sale agreement. Compare how much cash each needs, on which dates, and the total cost. If you plan to mortgage the balance later, get written confirmation of the conditions before committing to the developer's deadlines.
Updated 13 November 2026 · the iOffPlanDubai team.
What's the difference between a mortgage and a payment plan?
A mortgage creates a loan secured against the home. The lender assesses your income and the property before deciding what to offer. A developer plan sets the purchase instalments you agree with the seller; read the actual payment annex to see when each falls due.
You might use both: pay developer instalments during construction, then seek finance for a later balance. Ask the lender whether it can finance that property when you need the money.
| Compare | Mortgage | Developer payment plan |
|---|---|---|
| Amount and dates | Written finance offer and repayment schedule | Sale agreement and payment annex |
| Cash needed first | Purchase contribution and separately quoted costs | Reservation, initial instalment and separately quoted costs |
| Ongoing cost | Interest or profit, fees and other quoted charges | Agreed price, remaining instalments and other contract charges |
| Final payment | Check any remaining balance at the end of the term | Check the amount due at handover and any later instalments |
| Before relying on it | Read approval and release conditions | Read deadlines, payment triggers and cancellation terms |
Use the sale agreement checklist to keep the unit, price and payment annex together.
Sources · CBUAE, Mortgage Loan Regulations, effective 28 December 2013, as amended · CBUAE, disclosure standards · Checked 13 November 2026. The table is our document-comparison checklist.
Can a mortgage cover the remaining developer payments?
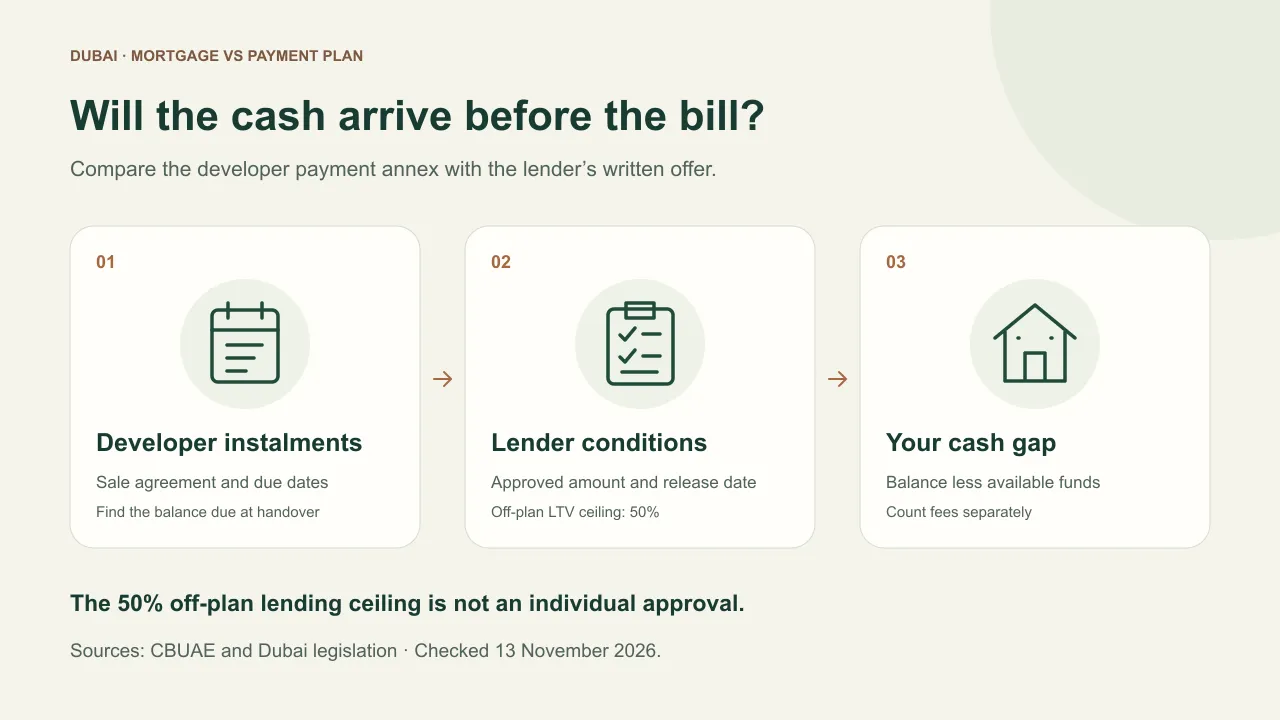
CBUAE caps mortgages for property bought off-plan at 50% loan-to-value, regardless of buyer category, purpose or property value. That's the loan as a share of the property's value, and a ceiling rather than a promise to lend.
Ask the lender how it will classify and value your purchase when funds are released. Get the approved amount, conditions and expected release date in writing. Ask what happens if its valuation leaves you short, or its offer expires before the developer's payment date.
Hypothetical example: a home costs AED 2,000,000, with AED 800,000 paid. The balance is AED 2,000,000 − AED 800,000 = AED 1,200,000. Assume the same off-plan valuation: AED 2,000,000 × 50% = AED 1,000,000. That leaves AED 200,000 to find, before fees. A smaller approval leaves a larger gap.
Source · CBUAE, Mortgage Loan Regulations, Article 3 · Checked 13 November 2026. The example uses invented, labelled assumptions; it isn't a finance offer.
How do you compare the full cost?
Ask for the lender's Key Facts Statement and written offer. CBUAE's disclosure standards require the approved amount, terms and cumulative repayments based on the initial interest or profit rate. For a changing rate, ask for the reference rate, margin and reset dates.
Put the repayment total beside the developer's price and instalments. Ask for separate charges, including valuation, registration and any required insurance or takaful. If you may repay early, request that calculation too. Your rate and fees need a current quote.
Watch out: “interest-free” doesn't give you the whole comparison. Ask whether the developer offers a different total price for another payment schedule. Compare dated quotes for the same apartment and specifications.
Keep the purchase costs separate from the annual service charges. You'll need both in your cash budget.
Source · CBUAE, Disclosure and Transparency, sections 2.1.1 and 2.1.3 · Checked 13 November 2026. Requesting comparable developer quotes is our suggested check.
What does a 60/40 payment plan actually tell you?
Hypothetical example: on a AED 2,000,000 purchase, 60% is AED 1,200,000 and 40% is AED 800,000. Those percentages alone don't tell you the dates or number of instalments.
Read the annex for the booking amount, construction payments and final balance. Ask whether the final payment is tied to a date, completion notice or handover step. If there's a post-handover balance, copy every later instalment into the same calendar.
The example is arithmetic, not an advertised plan. For a real project, the Skyhills Astra guide in Arabic shows which unit documents to request; it doesn't supply a payment schedule.
What should you check before the first payment?
If an offer uses MAG Kingdom, resolve the registered building name first. Put that same building and unit on the developer agreement and finance request.
- Match the home: use the same project, tower and unit number on the quote, agreement and finance request.
- Map the cash: list each due date, available cash and any lender funds still subject to conditions.
- Check the destination: ask for the project's escrow details and compare them with the registered project information.
- Read the exit terms: ask what happens if finance is declined, a payment is late or you want to resell.
Dubai's escrow law covers project accounts for off-plan purchaser and financier payments. Use the escrow guide to prepare that check. For the wider purchase, keep the off-plan due-diligence checklist beside your documents.
Sources · Dubai Legislation Portal, Law 8 of 2007, dated 6 May 2007 · Checked 13 November 2026. The numbered list is our preparation advice.
FAQ
Which option is cheaper?
You need comparable written quotes to answer that. Compare the same home's total price, finance repayments and separate charges, using the same intended ownership period. Check the cash needed on the largest payment date as well as the total.
Does post-handover mean I can pay whenever I like?
It means you need the dates and amounts that fall after handover. Put them beside any expected mortgage payments, then read the late-payment and early-settlement terms before asking to change the schedule.
Does paying the developer remove the need to register a mortgage?
DLD says a mortgage must be registered to be valid. If you're combining developer instalments with finance, ask the lender and DLD which registration steps apply to your transaction.
Source · DLD, mortgage registration FAQ · Undated, checked 13 November 2026.
Can I sell before I've finished the plan?
DLD's deferred-sale FAQ says resale requires a developer no-objection certificate. Ask about your remaining balance and the conditions for that certificate. Read the NOC guide before agreeing a resale deadline.
Source · DLD, deferred-sale FAQ · Undated, checked 13 November 2026.
Send the developer's payment annex to the lender. Ask it to mark which instalment it can cover, the amount and every condition that must be met first.
For Riverside Views Marine 1, start by matching the tower and apartment before comparing payment schedules.
For unfamiliar abbreviations in the offer, keep the Dubai property terms glossary beside the agreement.
Sources
- Central Bank of the UAE — Regulations Regarding Mortgage Loans — rulebook.centralbank.ae · checked
Circular 31/2013, effective 28 December 2013, as amended. Off-plan mortgage LTV ceiling is 50 percent for all purchaser categories, purposes and values. Approval remains individual.
- Central Bank of the UAE — Consumer Protection Standards, Article 2, Disclosure and Transparency — rulebook.centralbank.ae · checked
Official standards require a Key Facts Statement and written credit offer covering amount, conditions and repayments at the initial rate. See 2.1.1.19–22, 2.1.3.8–9. Early settlement costs require an example where applicable. No individual rate or fee is quoted.
- Dubai Legislation Portal — Law No. 8 of 2007, Escrow Accounts for Real Estate Development — dlp.dubai.gov.ae · checked
Law dated 6 May 2007. Defines a project escrow account for off-plan purchaser and financier payments and regulates developers receiving off-plan payments. The comparison checklist and illustrative payment schedule are editorial examples, not published developer terms.
- Dubai Land Department — Frequently Asked Questions — dubailand.gov.ae · checked
Undated official FAQ states mortgages must be registered at DLD to be valid. Its deferred-sale answer says resale requires a developer NOC. No standard developer instalment schedule or particular buyer's finance approval is established.
Next stepDubai properties service charges: fees and checks (2026) →
More in Ownership costs
Start here: Dubai properties service charges: fees and checks (2026)